Applied Digital posts 322% revenue jump as AI factory build-out scales
Applied Digital Corporation (Nasdaq: APLD) posted revenues of $341.9 million for its fiscal first quarter ending 31 August 2026, a 322% increase on the prior-year comparable period. The Dallas-headquartered company, which designs and operates purpose-built data centres for AI and high-performance computing workloads, attributed the surge primarily to tenant fit-out services and the commencement of base rental income from its growing campus portfolio.
On a non-GAAP basis, which strips out the results of majority-owned subsidiary ChronoScale Holdings, adjusted revenue came in at $300.4 million. Adjusted EBITDA reached $64.4 million, compared with $0.5 million in the same period a year earlier. The GAAP net loss attributable to common stockholders was $221.0 million, driven in part by a $49.5 million loss on derivative fair-value movements and $66.5 million in stock-based compensation.
Build-out and contracts
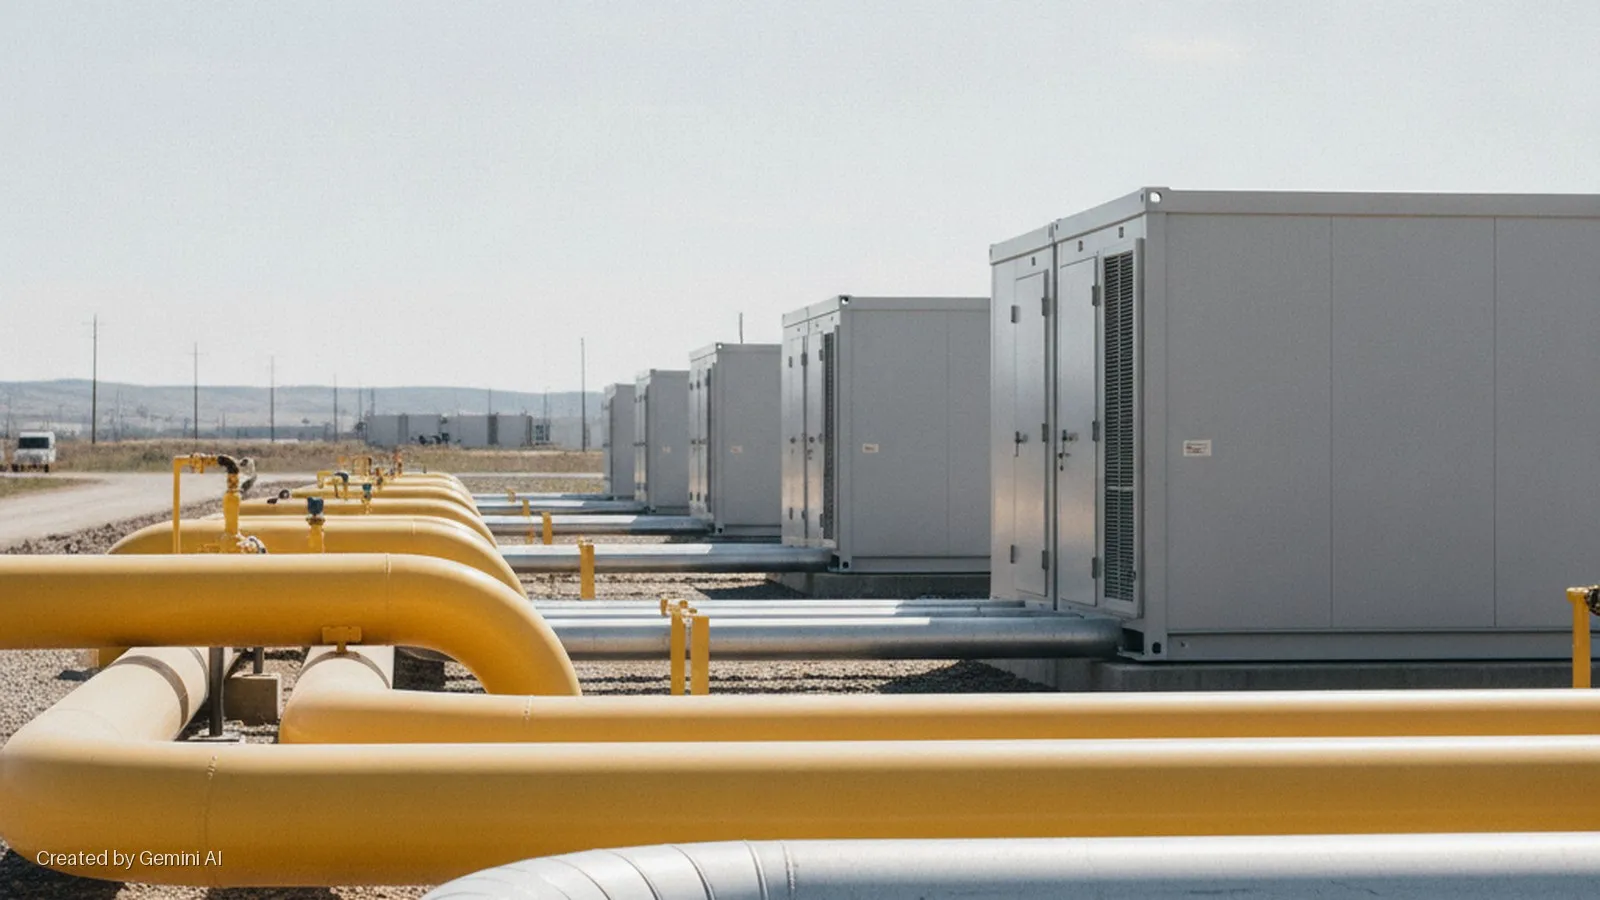
The quarter's operational highlights centred on Applied Digital's Polaris Forge 1 campus in Ellendale, North Dakota. Phase 1 of Building 2 (75 MW) was delivered ready for service on 1 July 2026, bringing total live capacity at the campus to 175 MW at quarter end. A further 75 MW phase followed on 1 October, pushing live capacity to 250 MW. The company closed $1.59 billion in 7% senior secured notes due 2031 to fund a third 150 MW building at the site and repay a bridge facility.
The broader lease portfolio now covers approximately 1.41 GW of critical IT load across five campuses, with contracted revenue of roughly $36 billion over initial base terms. Tenants include CoreWeave at Polaris Forge 1 and unnamed investment-grade hyperscalers at the remaining sites. A 210 MW, 15-year lease signed in June at Delta Forge 2 in Alabama represents approximately $5.2 billion of base-term contracted revenue alone.
Beyond the US, Applied Digital secured rights to up to 1 GW of potential power capacity in Finland, its first international move. The company also entered a Power Purchase Agreement with Base Electron, an independent power producer in which Applied Digital holds a roughly 10% equity stake, for capacity from a 1,200 MW natural gas-fired plant to be developed in North Dakota.
Market context and competitive position
Applied Digital's model of building large-scale, campus-based AI factories in low-cost, power-rich regions positions it alongside a small number of specialist hyperscale co-location providers, though it competes indirectly with the internal build programmes of the major cloud platforms. Chief executive Wes Cummins framed the company's land-and-power position as a structural moat: "As new data center development becomes more difficult in certain markets, we believe the scarcity value of established, powered, and community-supported campuses increases."
That thesis is increasingly tested by the industry's acute power constraint. Applied Digital's move into North Dakota gas-fired generation via Base Electron reflects a broader trend of data centre operators pursuing vertical integration in energy supply to secure build timelines that grid queues cannot guarantee. The Finland expansion is similarly power-led: the country offers a cool climate, stable grid, and room to scale at a moment when coastal US and European metro markets face permitting and capacity bottlenecks.
ChronoScale, Applied Digital's 96%-owned cloud subsidiary, announced a 50 MW AI compute deployment with Microsoft in North America, featuring NVIDIA GB300 NVL72 systems and liquid cooling. Applied Digital excludes ChronoScale from its non-GAAP metrics, treating its HPC hosting and data centre hosting businesses as the core operations for strategic evaluation.
As of 31 August 2026, the company held $3.7 billion in cash, cash equivalents, and restricted cash against $6.4 billion in debt, reflecting the capital intensity of its construction pipeline. Investors will be watching closely for the pace of capacity conversion from contracted to operational, and for the announcement of additional named hyperscaler tenants as the Dakotas campuses scale toward the 300 MW target the company expects to reach by end of calendar 2026.