Kia runs global PBV dealer programme ahead of PV7 launch
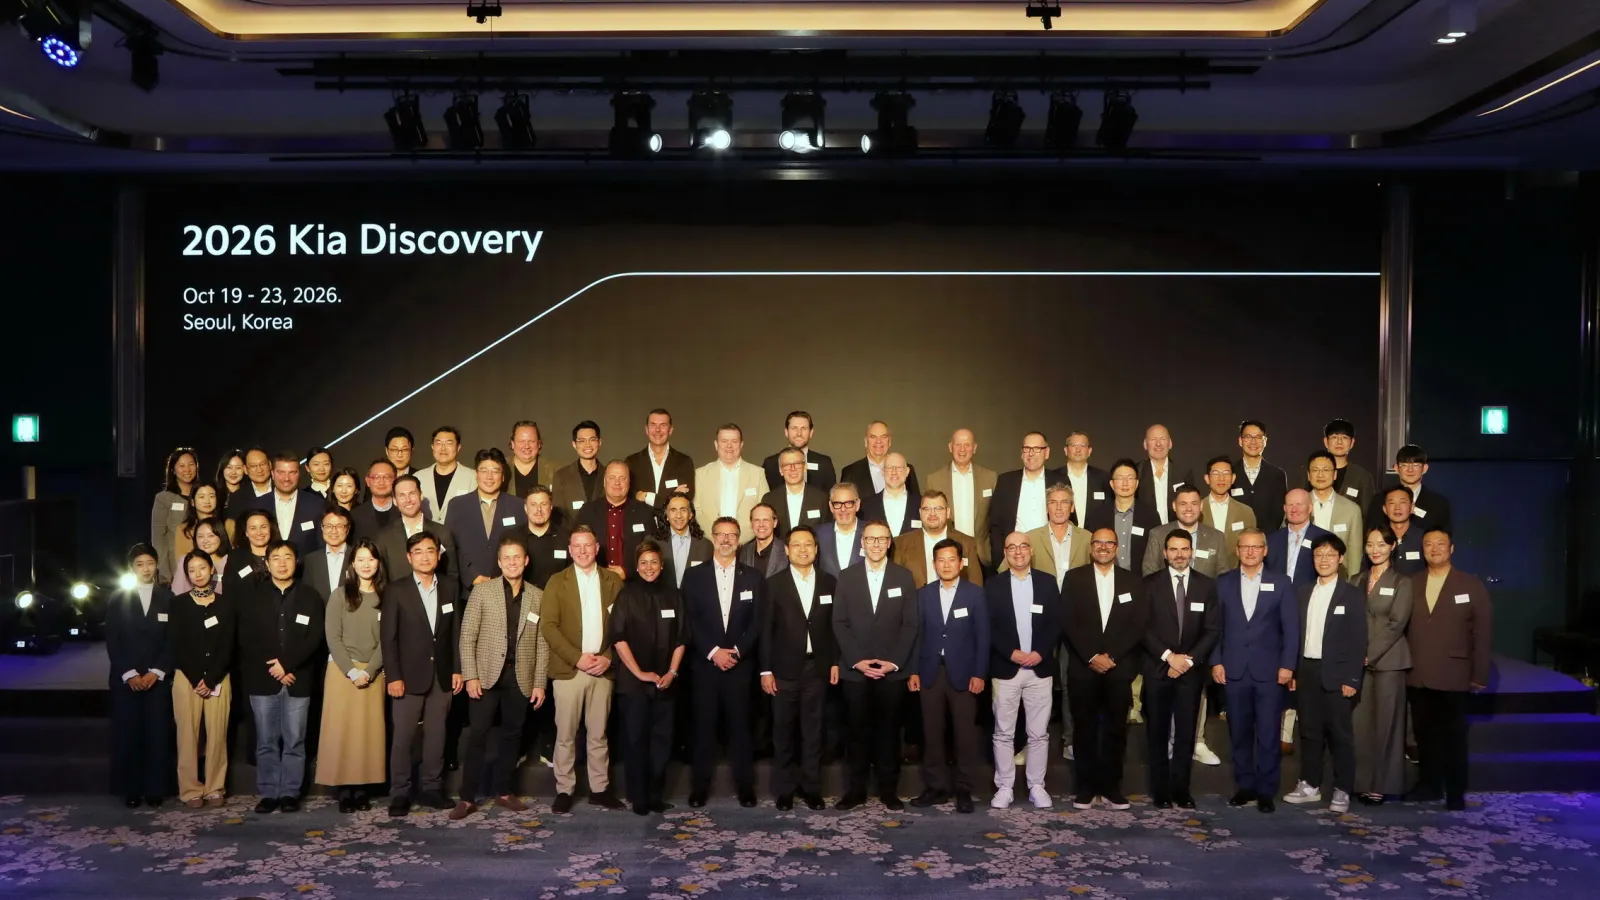
Kia has concluded its Discovery 2026 programme in South Korea, gathering dealer executives and business partners from Europe, North America, the Middle East and Asia-Pacific for a three-day session designed to strengthen alignment ahead of the company's next phase of expansion in purpose-built vehicles, known internally as the PBV segment.
The event, held from 20 to 22 October at facilities including Kia's headquarters, its Hwaseong electric-vehicle manufacturing plant, and a dedicated PBV experience centre, gave partners a structured look at the company's vehicle roadmap, software integration strategy and commercial model. No specific commercial agreements or fleet contract values were disclosed in connection with the programme.
Sales momentum and product roadmap
Kia said global sales of its PV5, the first model in the PBV line, exceeded 57,000 units by the end of August 2026, roughly 14 months after launch. The company presented that figure as evidence of market traction sufficient to justify broader platform investment.
The PV7, a larger-format PBV model unveiled at IAA Transportation, is scheduled to enter the market in 2027. A third model, the PV9, is planned for 2029. Kia's stated target is to sell 232,000 PBV units annually by 2030 across all three models, a target the company outlined at its 2026 CEO Investor Day. No regional volume split or pricing information accompanied the release.
The PBV architecture combines electric drivetrains with purpose-specific body configurations, proprietary software and associated fleet services, positioning the vehicles as a managed mobility solution rather than a standalone product. Kia describes this integration of hardware, software and service as the defining commercial proposition for the segment.
Market context and competitive landscape
The commercial electric van and last-mile delivery segment has attracted considerable investment from both incumbent carmakers and specialist entrants. Stellantis, Ford and Volkswagen all offer or have announced purpose-built electric light-commercial vehicles targeting fleet and logistics operators, while specialist players such as Arrival and Volta Trucks demonstrated the risks of the capital-intensive manufacturing model at scale. Kia's approach of anchoring the PBV business within an established global manufacturing and distribution network, rather than building a standalone operation, gives it a structural cost advantage that smaller entrants struggled to replicate.
Dealer alignment is a meaningful operational variable in this segment. Fleet and logistics customers typically require local service and upfitting support, meaning the quality of the dealer network directly affects total cost of ownership and contract retention. The Discovery programme appears intended partly to address that dependency by ensuring international partners are equipped to serve fleet buyers rather than retail consumers, who have different service-interval and configuration requirements.
Regulatory and standards read-across
The EU's Commercial Vehicle CO2 standards, which set binding fleet-average emissions targets for van manufacturers from 2025 onwards, are accelerating electrification across the European fleet market and creating a regulatory tailwind for PBV programmes like Kia's. In the UK, the Zero Emission Vehicle mandate requires a rising proportion of new van sales to be electric, with targets stepping up through to 2030, the same year Kia has set as its volume milestone. Fleet operators procuring at scale will also be navigating the EU's Battery Regulation, which introduces supply-chain due-diligence and carbon-footprint disclosure requirements for traction batteries from 2024 onwards.
Kia's 2030 target of 232,000 PBV units annually will be tested against delivery execution on the PV7 and PV9 programmes, the pace at which logistics operators commit to electric fleets, and the company's ability to build out software and service revenue alongside hardware sales.